I spent 10 years in the military as a Combat Controller. Like a lot of veterans, when I left the service, I had a long list of things to figure out. What came next professionally. Where I was going to live. How I was going to translate my military experience into the civilian world.
And somewhere on that list was my TSP. I had spent years contributing to it, but if I'm being completely transparent, I didn't really understand my options when it came time to decide what to do with it.
I eventually rolled my TSP into an employer-sponsored 401(k). Was that necessarily the wrong decision? No. But looking back, I wish I had understood the decision I was making.
Here are three things I understand differently today.
1. You Have More Options Than You May Realize
When I left the military, my thinking was pretty simple: I had a TSP. I had a new employer with a 401(k). Moving the money from one retirement account into the other seemed like the logical thing to do.
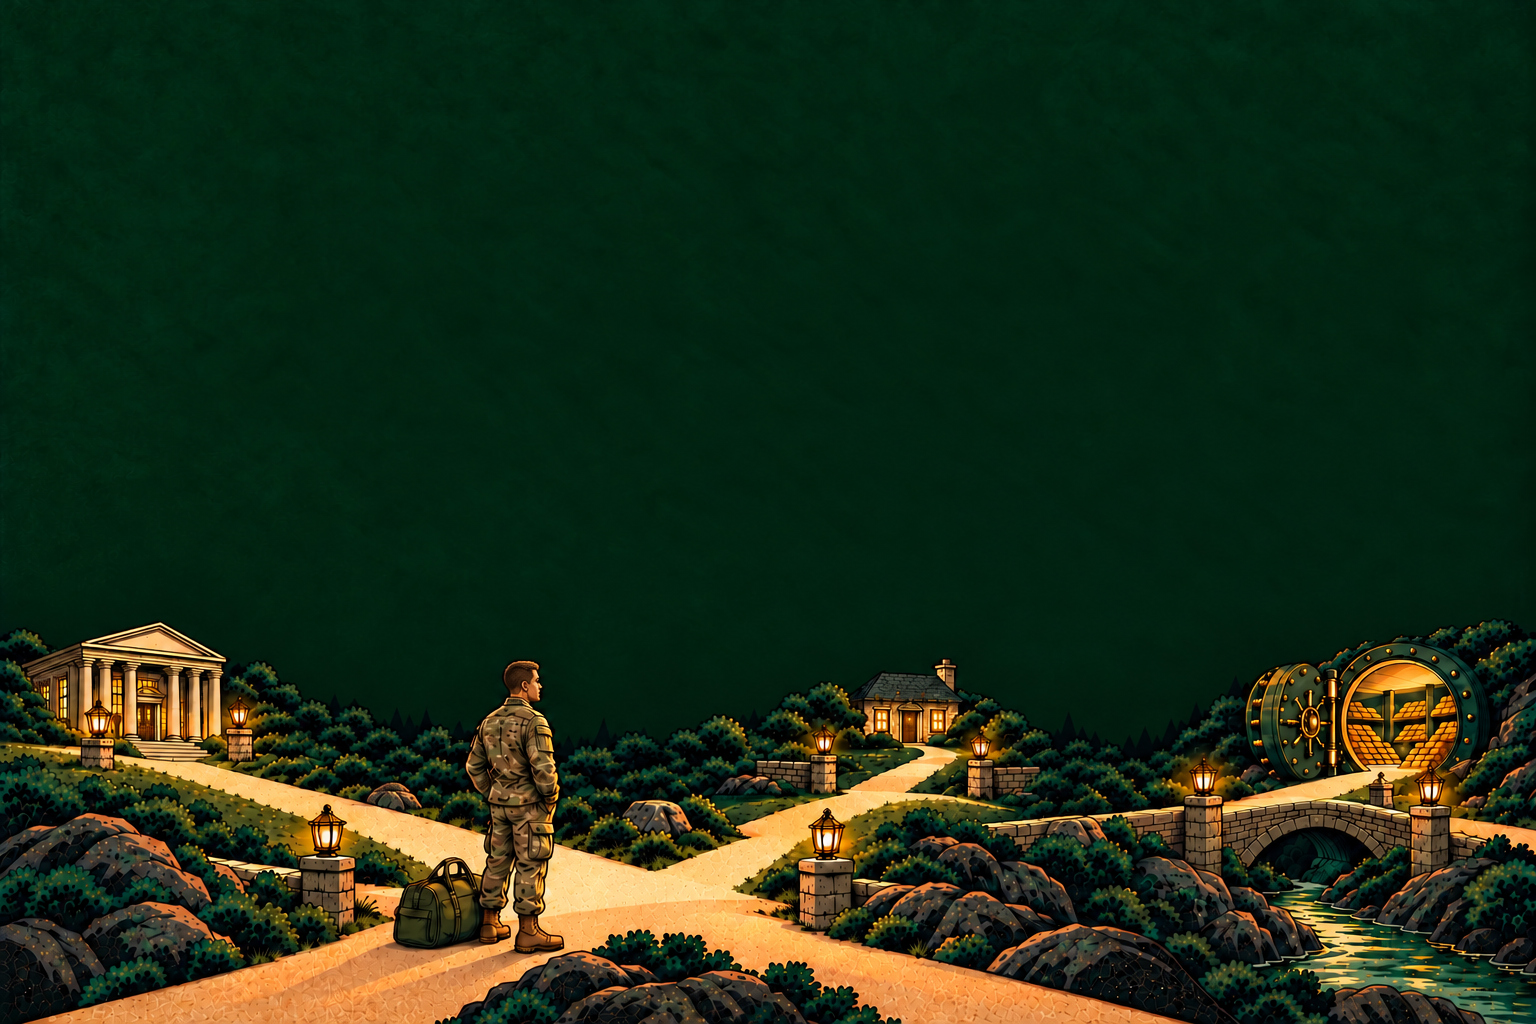
What I didn't realize was that I had choices. Depending on your individual circumstances and the rules that apply, leaving military service doesn't automatically mean you have to move everything into your next employer's retirement plan.
You may be able to leave money in the TSP. You may be able to roll eligible funds into another employer-sponsored retirement plan. You may be able to roll eligible funds into an IRA. Each path has its own considerations, and I wish I had taken the time to learn what they were.
2. A Rollover Isn't Just Paperwork. It's an Investment Decision.
At the time, I viewed my rollover mostly as an administrative task. Move retirement account A into retirement account B. Done.
What I didn't appreciate was that where you hold your retirement assets can affect the investment choices available to you. The TSP has its own investment structure. An employer-sponsored 401(k) has another. IRAs can provide a different universe of investment choices. Certain self-directed retirement accounts can provide access to additional asset classes, including certain qualifying physical precious metals.
That doesn't mean everyone leaving the military should move their TSP into an IRA. It certainly doesn't mean every veteran should own gold. It means a rollover deserves more thought than I gave mine. Investment selection, fees, diversification, liquidity, taxes, withdrawal rules and your overall retirement strategy all deserve consideration.
3. Doing Nothing Should Still Be a Decision
Military transition throws a thousand decisions at you simultaneously. Your TSP can easily become one of those things you either deal with quickly or simply forget about. But for many service members, that account represents years, sometimes decades, of saving and investing. It deserves more than an afterthought.
Keeping assets in the TSP, rolling eligible assets into a new employer's plan, or moving eligible assets into an IRA can all make sense depending on the individual. What matters is understanding what each path means for you.
My perspective on all of this has changed considerably since I separated. Part of that is simply life experience. Part of it is because building American Wealth Group has put me much closer to conversations around retirement assets, diversification and the different ways people choose to protect what they've spent years building. The irony isn't lost on me. Today, I spend a lot of time thinking about questions I barely knew to ask when I was making my own transition out of the military.
If I could go back, I wouldn't necessarily tell the younger version of myself to make a different choice. I'd tell him to ask better questions first.
The Takeaway
If you're leaving the military, or you left years ago and still have a TSP, don't start by asking “Where should I move my money?” Start with better questions:
- What do I own today?
- What happens if I leave it where it is?
- What changes if I move it?
- What will I pay in fees?
- What investment choices will I gain or lose?
- How does this fit into the rest of my retirement plan?
You don't need to become a retirement expert. You just need to know enough to make an informed choice about something you spent years building.
A Simple Next Step
Before moving anything, pull up your most recent TSP statement and spend 30 minutes understanding exactly what you have. Look at your balance, how it's currently invested, your beneficiaries and the funds you're holding. Then compare the choices available to you if you keep the TSP versus moving eligible assets elsewhere.
Write down the questions you can't answer. Those questions are where I'd start. You earned that retirement. Give it the same level of attention you gave to earning it.
Want to Talk Through Your Options?
If you have a TSP, or you are about to separate and are starting to sort through your options, our free guide walks through diversification, rollovers, custody and costs, plus the questions worth asking before you move anything. Or reach out and we will talk it through with you.*